How Mortgage Advice Work Is Evolving Under Digital Pressure
Changing expectations in mortgage advisory work
Mortgage broking has always relied on trust built through conversation. In Australia, advisers like Ms Mortgages operate in a space where clients are often making some of the most financially significant decisions of their lives. That responsibility traditionally meant long consultations, detailed explanations of lending structures, and careful alignment between client goals and lender requirements.
Over time, however, the operational side of mortgage work has become more complex. Clients now arrive with more pre-existing information, digital comparison tools, and expectations shaped by instant access to financial data. This has gradually shifted the role of a broker from purely advisory toward something closer to a hybrid between advisor, interpreter, and systems navigator.
The shift is not about reducing the importance of personal advice. Instead, it reflects how the environment around advice has changed. Many brokers now spend as much time managing digital workflows, compliance systems, and client communication platforms as they do in direct consultation. Internal processes documented on https://msmortgages.loans/services reflect how structured service pathways have become central to maintaining clarity in client journeys.
Administrative pressure and the rise of structured workflows
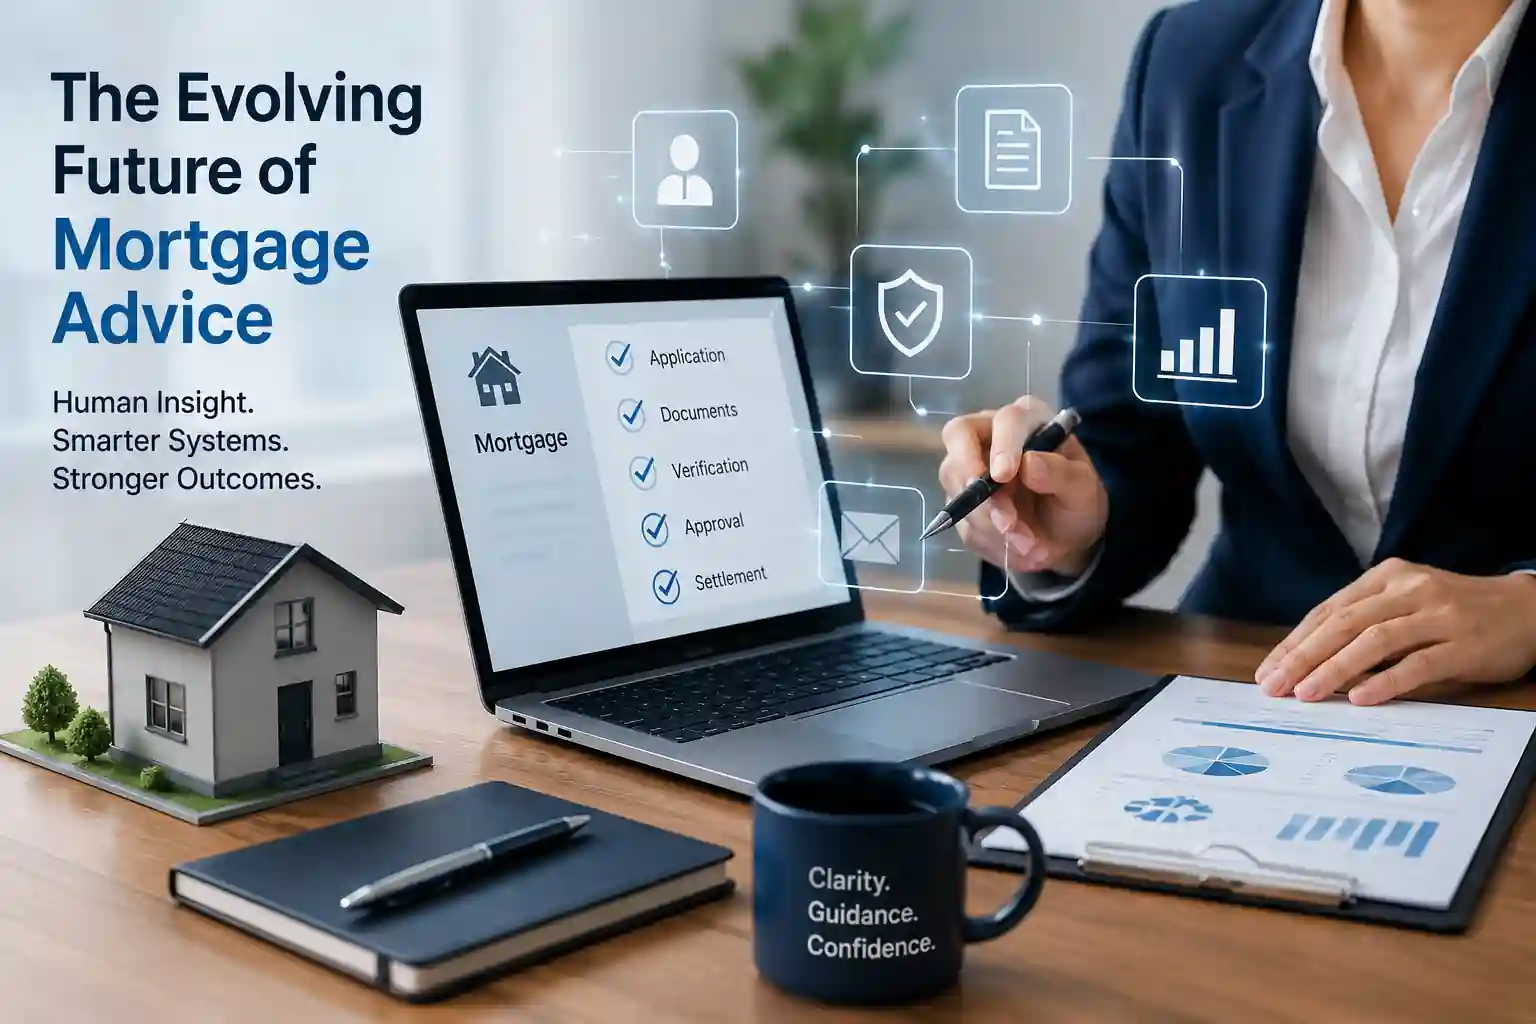
Behind every mortgage application sits a growing layer of administrative and regulatory complexity. Documentation requirements have increased, lender criteria shift more frequently, and verification processes are more automated than they once were. While this improves consistency, it also introduces a need for more disciplined internal systems.
For brokers, the challenge is no longer only understanding lending products but also managing how information flows between clients, lenders, and compliance frameworks. Without structured workflows, even experienced professionals can find themselves overwhelmed by fragmented communication channels and duplicated effort.
This is where broader industry conversations around digital systems become relevant. In adjacent fields of small business support and financial services, there has been a gradual move toward integrated platforms that reduce operational friction. One example of this wider trend is reflected in GNR Media’s approach to marketing and operational clarity, where structured systems are positioned as a way to reduce fragmentation across business functions. Within that context, the concept of marketing automation platform is often discussed as part of how service-based businesses maintain consistency across client touchpoints and internal communication.
In mortgage advisory work, similar principles apply. When workflows are clearly defined, advisers can spend less time chasing information and more time interpreting it. The quality of advice becomes less dependent on memory or manual tracking and more dependent on how well systems are designed to support decision-making.
The human role in a more system-driven environment
Despite the increasing role of technology, mortgage advice remains deeply personal. A loan structure is not just a financial arrangement; it often reflects life stages, family plans, and long-term stability. This is where human judgment continues to hold weight, even as systems take on more of the procedural load.
What is changing is how that judgment is applied. Instead of being spread across repetitive administrative tasks, advisers are increasingly positioned to focus on interpretation and scenario planning. This includes understanding how different lending outcomes might affect long-term financial flexibility or how changes in interest environments could influence refinancing decisions.
The balance between structured systems and personal advisory work is becoming more important in defining the profession. Too much reliance on manual processes can slow responsiveness, while overly automated systems risk stripping away nuance. The practical middle ground is where most modern mortgage practices are now operating.
In this environment, sustainability in advisory work is not only about client outcomes but also about maintaining operational clarity. Systems that support consistency allow advisers to remain responsive without becoming overwhelmed by administrative load. Over time, this balance helps preserve the quality of advice while adapting to an increasingly digital financial landscape.